
Key Takeaways
- RWA tokenization turns real-world assets into digital tokens to trade on blockchain. Assets like real estate, bonds, gold, private credit, etc. one of those.
- The RWA tokenization process involves multiple steps. Such as checking asset ownership and value, setting up the legal structure, choosing a token standard, developing smart contracts and issuing tokens to verified investors
- An real world asset tokenization development costs around 35k to 110k for an MVP. And the enterprise-level platform can cost over $1 million depending on advanced features, multiple asset support.
- SPV structures work well for physical assets like property, real-estate etc. While direct tokenization is often more suitable for financial assets like bonds, private credit & debts.
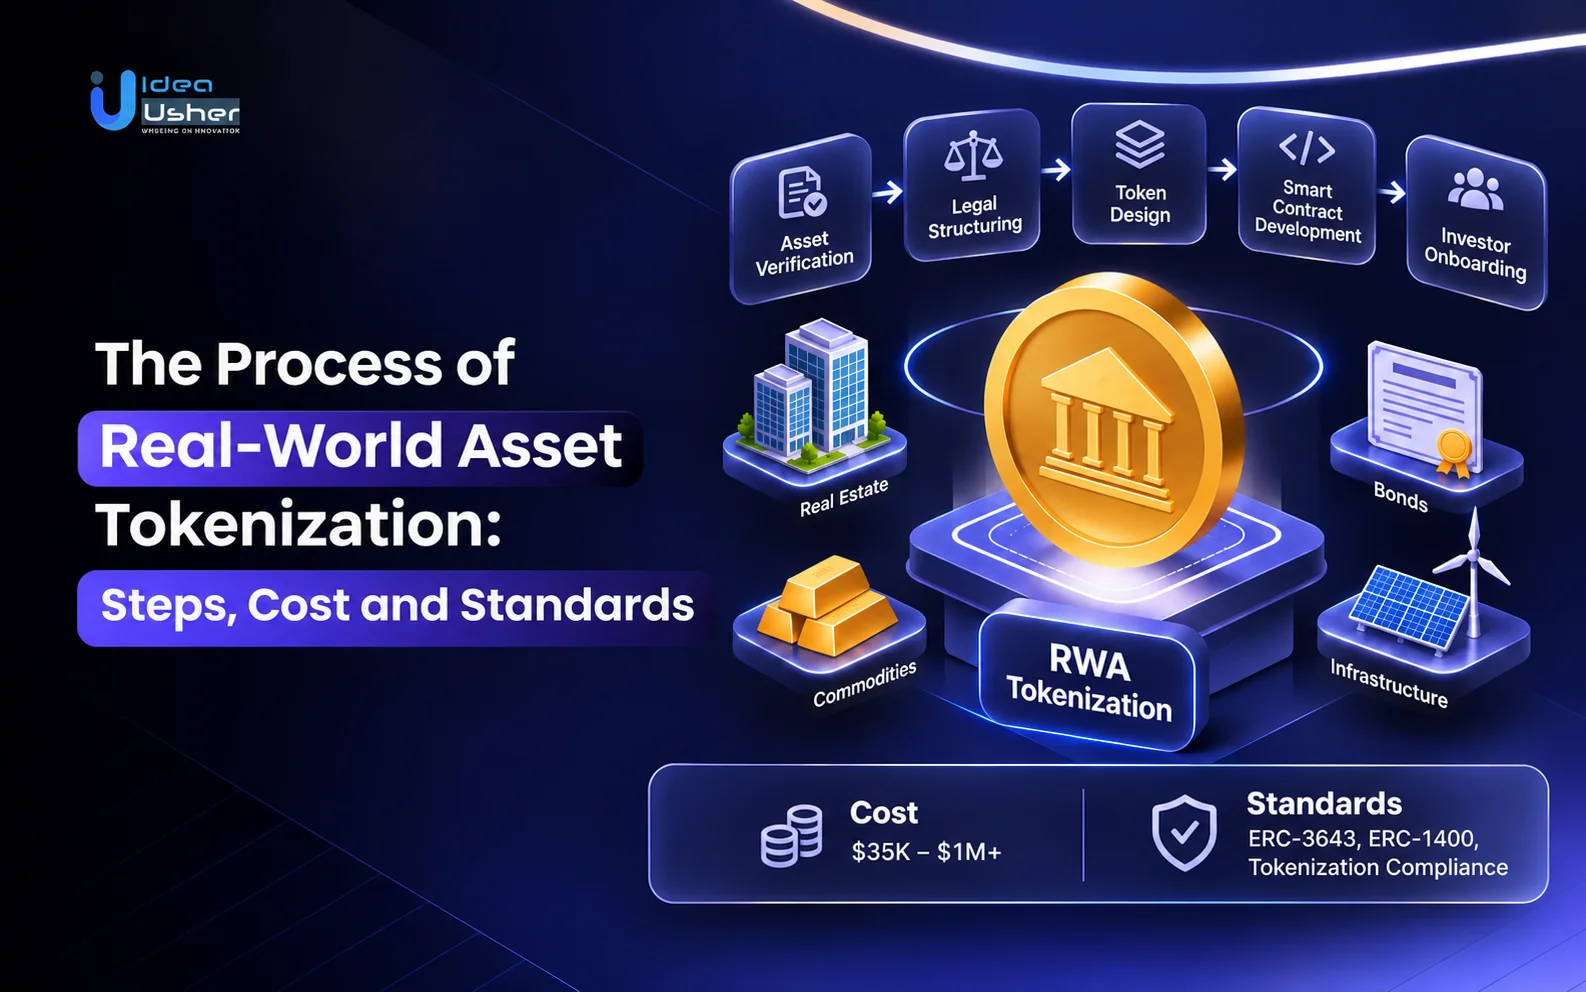
Real-world asset tokenization turns financial assets into digital tokens on the blockchain that represent ownership or contractual rights. The process includes asset verification, legal structuring, token design, blockchain selection, smart contract development and investor onboarding. The cost to build a real world asset tokenization development can range from $35,000 to $1 million, depending on platform complexity, asset-type support and compliance. Token standards like ERC-3643 and ERC-1400 support programmable transfer restrictions and token security management.
Beyond creating tokens, successful tokenization requires linking blockchain records to legal ownership and verified asset information. Businesses must define how assets will be held, who can invest, how transfers will work and how payments or redemptions will be handled. These decisions influence platform architecture, regulatory requirements, development complexity and long-term asset management.
In this blog, we will explain the real-world asset tokenization process, covering each stage, essential standards, blockchain infrastructure, compliance requirements and cost factors that influence the implementation of an RWA tokenization platform.
What Are Real-World Assets (RWAs)?
Real-world assets (RWAs) are physical or traditional financial assets such as real estate, government bonds, commodities and invoices that are converted into digital tokens on a blockchain. This process, known as tokenization, allows off-chain value to be bought, sold and managed within decentralized finance (DeFi) ecosystems.
A. How RWA Tokenization Works
RWA tokenization links physical and financial assets to blockchains by establishing legal ownership, verifying data and issuing digital tokens. Turning a physical or traditional asset into a digital token involves three core steps:
- Off-Chain Formalization: A legal entity or custodian acquires and holds the physical asset or financial security, establishing clear legal ownership and valuation.
- Information Bridging: Data about the asset’s value, legal status and audit reports are brought onto the blockchain using decentralized data feeds called oracles.
- On-Chain Minting: A smart contract issues digital tokens that represent fractional or full ownership rights to the underlying asset, enabling instant peer-to-peer trading.
B. Key Benefits and Risks
RWA tokenization offers greater investment accessibility, liquidity and transparency, but also introduces custody and regulatory challenges. The following table summarizes its key benefits and risks.
| Category | Key Factors |
| Benefits | Fractional Ownership: Lowers the minimum capital required to invest in expensive assets like commercial property. 24/7 Liquidity: Enables continuous global trading and faster settlement compared to traditional banking hours. Transparency: Records ownership history and automated dividend payouts publicly on a blockchain ledger. |
| Risks | Custody and Counterparty Risk: Investors rely on a centralized company to safely hold the physical asset and honor token redemptions. Regulatory Uncertainty: Cross-border securities laws and tax rules for tokenized assets vary widely and continue to evolve. |
Which Asset Classes Can Be Tokenized as RWAs?
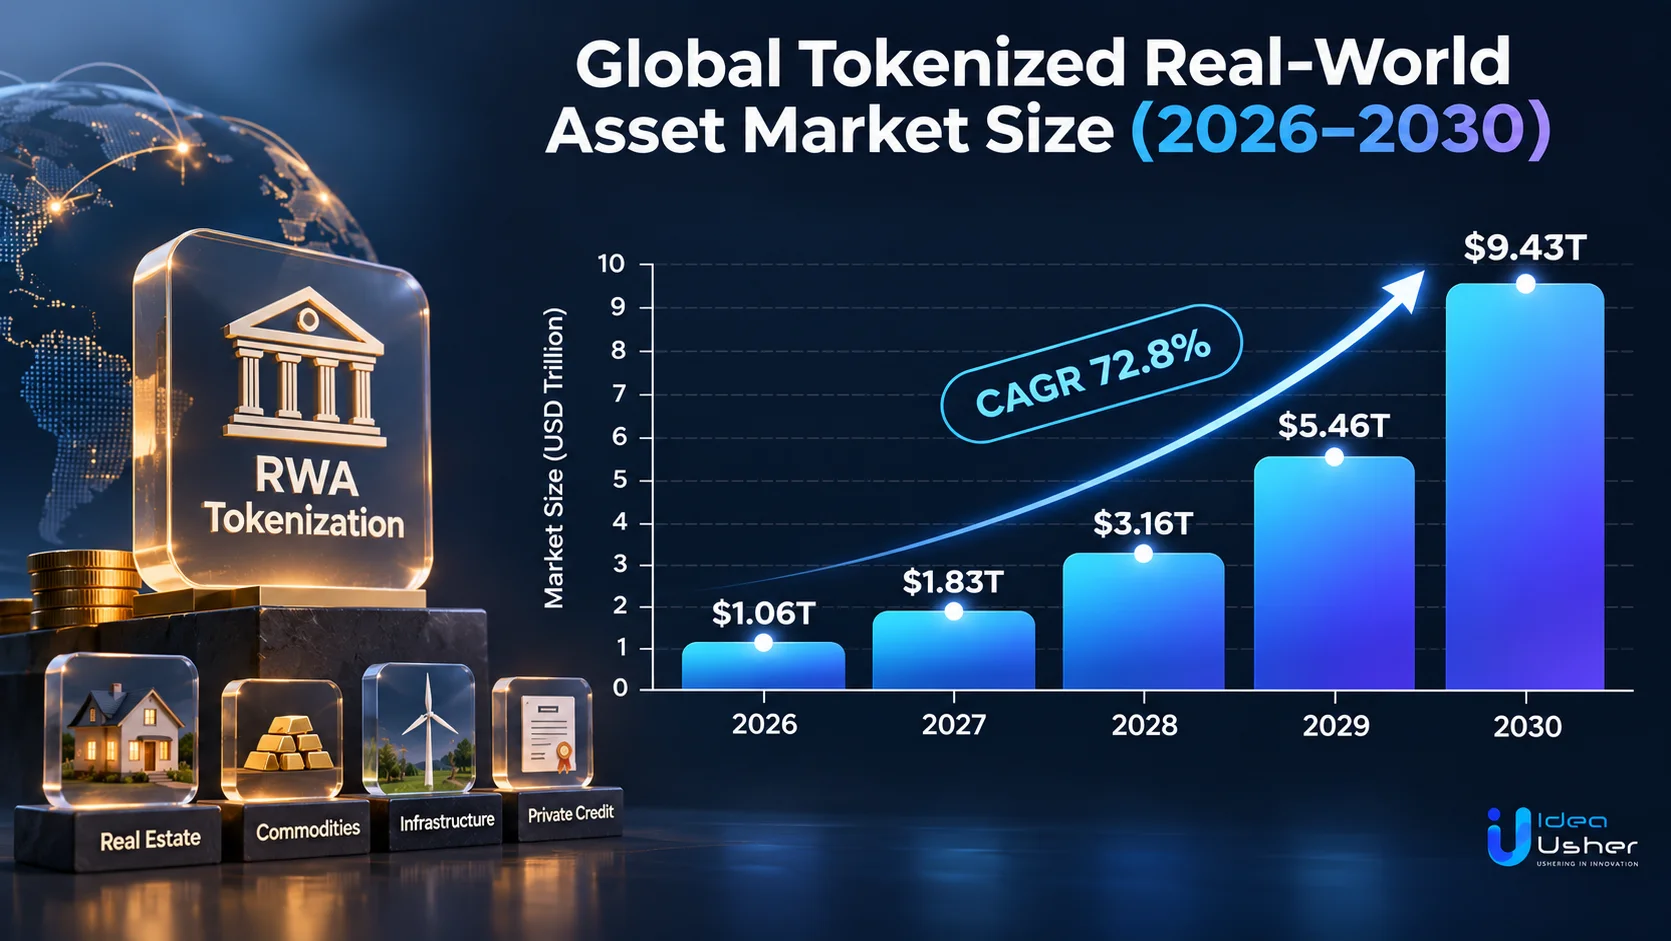
The global RWA tokenization market is projected to grow from $612.71B in 2025 to $1.06T in 2026 and is predicted to reach $9.43 trillion by 2030, at a 72.8% CAGR.
RWA tokenization turns assets like property, financial instruments, commodities, currencies, credits and IP into blockchain tokens. These tokens convey ownership or contractual rights, with legal, valuation and custody requirements varying by asset class.
According to RWA.xyz (November 10, 2026), tokenized real-world assets reached $40.04B in distributed value, $402.73B in represented value and $5.71M asset holders.
A January 2026 EY-Parthenon and Coinbase survey found that 64% of asset managers were interested in tokenizing assets, up from 40% in 2025, while investor interest rose from 57% to 63%.
The following comprehensive table showcases various real-world asset (RWA) categories, detailing the exact underlying assets, legal mechanisms and prominent example platforms driving market adoption:
| RWA Asset Type | What Gets Tokenized | Real-World Platform Examples |
| Government Bonds & Money Market Funds | U.S. Treasury bills, sovereign debt & short-term cash funds. | • BlackRock (BUIDL) – Institutional tokenized liquidity fund issued via Securitize. • Ondo Finance – Offers tokenized Treasuries (OUSG) and yield-bearing notes (USDY). • Franklin Templeton – Operates the Benji Investments platform for on-chain money market funds. |
| Private Credit & Debt | Business loans, invoices, trade finance receivables & home equity credit. | • Centrifuge – Connects real-world borrowers and credit funds (like Apollo) to DeFi liquidity. • Maple Finance – Institutional corporate lending and credit pools. • Figure Technologies – Tokenizes home equity lines of credit (HELOCs) and mortgages. |
| Real Estate | Residential rentals, commercial buildings, hotels & land development projects. | • Lofty – Fractional ownership in U.S. single-family rental properties. • RedSwan – Institutional-grade commercial real estate marketplaces. • Blocksquare – White-label infrastructure for tokenizing property portfolios. |
| Commodities & Precious Metals | Physical gold, silver, oil, natural gas & agricultural goods held in vaults. | • Paxos (PAXG) – Tokens backed 1:1 by physical London Good Delivery gold bars. • Tether Gold (XAUt) – Physical gold bullion stored in Swiss vaults. |
| Equities & Private Funds | Publicly traded stocks, ETFs, private equity stakes & venture capital funds. | • Backed Finance – Issues fully collateralized tokens tracking public stocks and ETFs. • Securitize – Tokenizes private equity funds (e.g., KKR, Hamilton Lane). • ADDX – Regulated exchange for fractional private equity and hedge funds. |
| Fiat Currencies (Stablecoins) | Traditional currencies like the U.S. Dollar or Euro held in bank reserves. | • Circle (USDC) – Regulated fiat-backed digital dollars. • Tether (USDT) – Largest fiat-pegged liquidity token across global exchanges. |
| Environmental & Carbon Assets | Carbon credits, renewable energy certificates & solar farm revenues. | • Toucan Protocol – Bridges verified carbon credits onto public blockchains. • KlimaDAO – Infrastructure and liquidity marketplace for on-chain carbon assets. |
| Fine Art, Luxury & Collectibles | Blue-chip paintings, rare watches, fine wine& memorabilia. | • Masterworks – Securitized fractional shares in contemporary art (exploring on-chain rails). • Courtyard.io – Vaults and tokenizes graded physical collectibles and trading cards. |
| Intellectual Property (IP) | Music royalties, film rights, patents & software licenses. | • Royal – Allows fans to buy tokenized shares of music streaming royalties. • Story Protocol – On-chain infrastructure for registering and licensing programmable IP. |
How to Tokenize Real-World Assets: 8 Steps Explained
Real-world asset (RWA) tokenization converts physical and traditional assets like commercial real estate, private equity, fine art and Treasury bills into digital tokens. Beyond minting tokens, it requires legal structuring, asset verification, smart contract development, investor onboarding and ongoing management.
The following table provides an overview of the eight stages, including the teams responsible, key deliverables and estimated timelines.
| Step | Owner | Output | Timeline |
| 1. Asset Identification, Due Diligence and Valuation | Asset owner, valuation specialist | Verified asset details, ownership documents and valuation report | 1–3 weeks |
| 2. Legal Structuring and Regulatory Assessment | Legal counsel, compliance team | Legal classification, jurisdiction review and regulatory pathway | 2–6 weeks |
| 3. Token Design and Economic Rights Definition | Legal counsel, financial structuring team | Ownership structure, investor rights and token economics | 1–4 weeks |
| 4. Blockchain, Token Standard and Custody Selection | Blockchain architect, technical team | Selected network, token standard and custody architecture | 1–2 weeks |
| 5. Smart Contract Development, Integration and Auditing | Developers, platform engineers, security auditors | Audited token contracts and integrated platform components | 4–12 weeks |
| 6. Investor Onboarding and Token Issuance | Issuer, transfer agent, technical team | KYC/AML-approved investors, minted tokens and issuance records | 1–3 weeks |
| 7. Asset Servicing, Reporting and Corporate Actions | Asset manager, compliance team | Investor records, distributions and ongoing reports | Ongoing |
| 8. Secondary Market Trading and Token Redemption | Issuer, marketplace operator, legal team | Approved transfer arrangements and redemption process | 2–8 weeks |
These stages form the broader RWA tokenization lifecycle. Let’s examine how each stage works, what it involves and the key decisions businesses need to make.
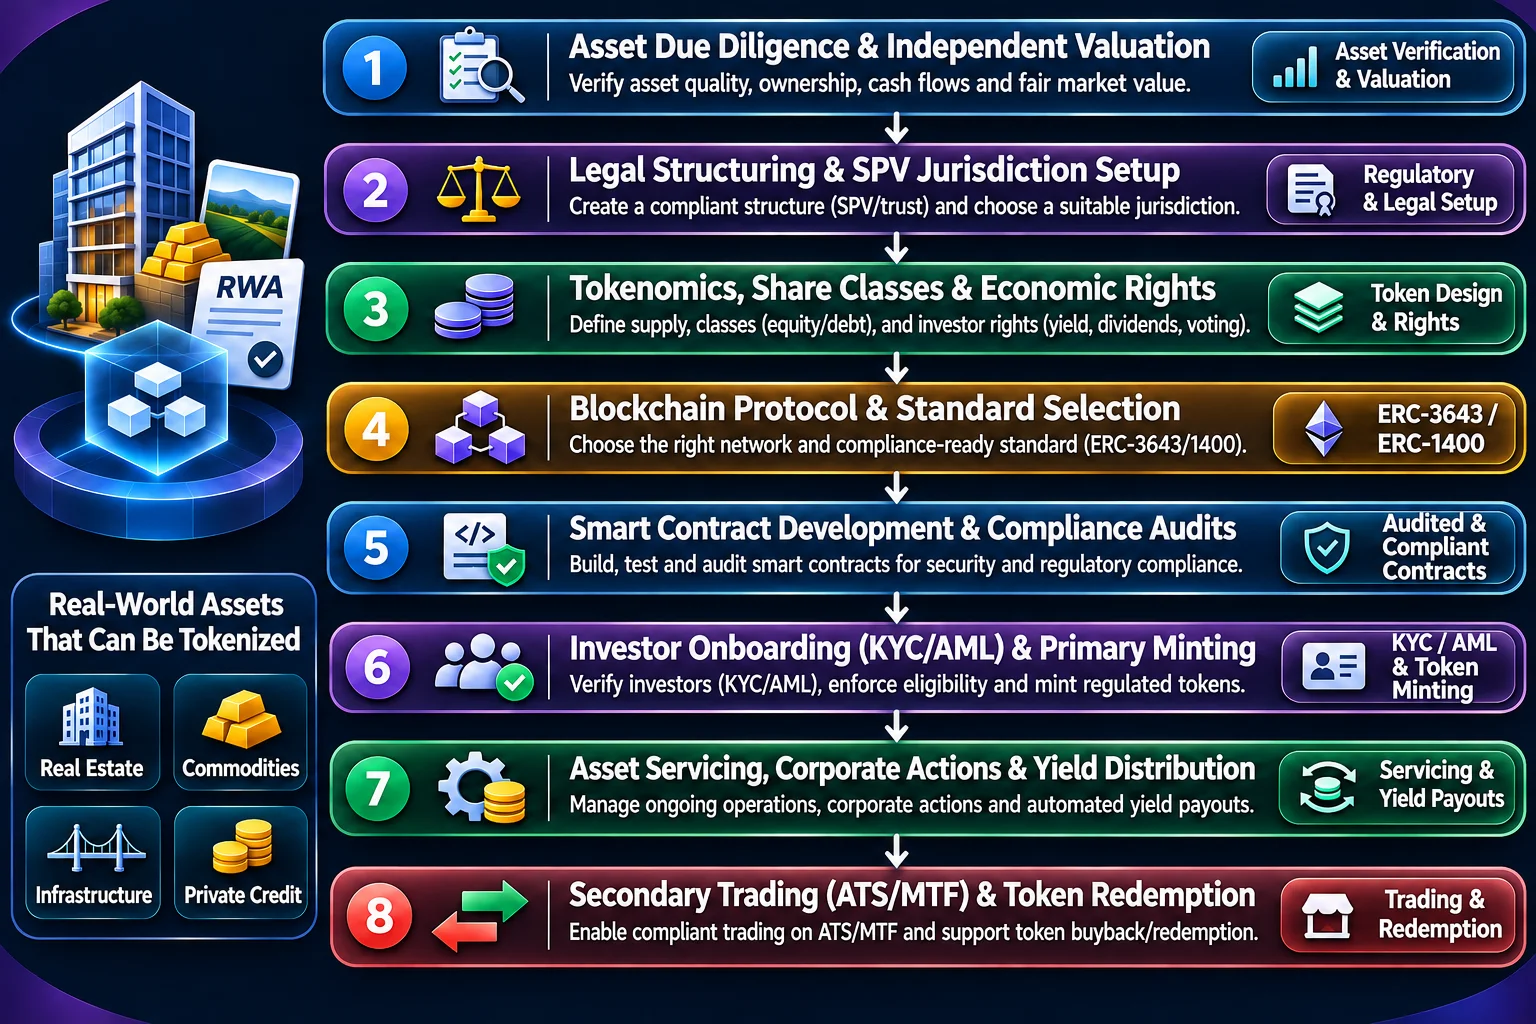
Step 1: Asset Identification, Due Diligence and Valuation
Before writing code or issuing digital tokens, the issuer must establish clear, unencumbered legal title to the physical or financial asset.
- Ownership Verification & Title Search: Verify asset ownership records, property deeds or corporate stock ledgers. Audit existing liens, mortgages, encumbrances or tax liabilities that could cloud legal claims.
- Independent Asset Valuation: Engage accredited third-party appraisers, auditing firms or valuation specialists to establish an objective fair market value (FMV). This valuation defines the initial base capitalization for tokenized fractional shares.
- Custody & Physical Inspection: For tangible assets (e.g., real estate, commodities, fine art), physical condition reports and secure custodial storage agreements (e.g., freeport vaults for physical gold or art) must be executed before tokenization.
Step 2: Legal Structuring and Regulatory Assessment
Blockchain tokens are digital representations of legal claims. Creating an enforceable connection between an on-chain token and an off-chain asset requires tailored legal structures.
- SPV Formation: Issuers establish a bankruptcy-remote Special Purpose Vehicle (SPV) such as a Delaware LLC, Cayman SPC or Luxembourg SA to hold absolute legal title to the underlying asset.
- Securities Qualification & Exemptions: Because RWA tokens are legally classified as securities, issuers must file under appropriate regulatory exemptions based on target jurisdictions:
- United States: Regulation D (506b/506c for accredited investors), Regulation S (offshore non-US investors) or Regulation A+ (public mini-offering).
- European Union: Compliance with Markets in Financial Instruments Directive II (MiFID II) and Prospectus Regulation framework.
- Investor Rights Enforceability: Legal agreements (e.g., Operating Agreements, Subscription Agreements, Debentures) must explicitly state that holding and transferring the digital token constitutes a legally binding ownership or debt claim on the SPV.
Step 3: Token Design and Economic Rights Definition
Tokenomics for RWAs must translate complex corporate agreements into unambiguous parameters suitable for smart contract execution.
- Fractionalization Math: Determine the total token supply and fractional unit size. For example, a $10,000,000 real estate asset divided into 10,000,000 tokens yields a base value of $1.00 per token.
- Economic Rights Rights Mapping:
- Equity Rights: Direct entitlement to net rental yields, asset appreciation and voting distribution rights.
- Debt Rights: Fixed or variable interest rates, coupon payment frequencies and debt maturity repayment schedules.
- Transfer & Lock-Up Restrictions: Define statutory lock-up periods (e.g., Rule 144 one-year holding requirements under US SEC rules) and secondary transfer eligibility conditions within the token’s parameters.
Step 4: Blockchain, Token Standard and Custody Selection
Selecting the technical stack determines transaction processing speed, gas fee structures, regulatory compliance tooling and institutional interoperability.
- Blockchain Network Selection: Choose public EVM L1/L2 networks (Ethereum, Polygon, Arbitrum), specialized RWA chains (Polymesh) or permissioned enterprise networks (Hyperledger Fabric) based on finality time, gas costs and institutional requirements.
- Security Token Standard Selection: Standard utility tokens (ERC-20 / ERC-721) lack built-in transfer controls. RWA implementations rely on specialized permissioned standards:
- ERC-3643 (T-REX): Uses an On-Chain Identity (ONCHAINID) registry system. Automatically verifies recipient KYC/AML claim attestations before allowing any wallet-to-wallet transfer to succeed.
- ERC-1400: A modular security token protocol supporting partitioned balances (share classes), document management and forced controller transfers for recovery procedures.
- Institutional Custody Setup: Integrate qualified digital asset custodians (e.g., Fireblocks, BitGo, Coinbase Custody) featuring Multi-Party Computation (MPC) vault infrastructure for securing master minting keys and corporate treasuries.
Step 5: Smart Contract Development, Integration & Auditing
The smart contract layer converts compliance frameworks and corporate actions into automated, immutable code.
- Compliance Engine Integration: Program jurisdiction-specific rules into smart contracts including investor caps (e.g., 2,000 holders under SEC Section 12(g)), country-level allowlist/blocklist filters and accredited investor checks.
- ERP & Financial System Hooks: Build Web3 API middleware to connect smart contract events with ERP databases, banking rails (ACH/FedNow/SWIFT) and real-time cap-table software.
- Third-Party Security Audits: Conduct formal verification and vulnerability audits through specialized smart contract firms to identify reentrancy vulnerabilities, logic bugs and privilege escalation risks.
Step 6: Investor Onboarding and Token Issuance
Primary distribution onboarding converts prospective buyers into verified, compliant token holders.
| Onboarding Stage | Operational & Technical Actions | Output / Result |
| 1. Identity Verification | Biometric liveness check, government photo ID scan, PEP & sanctions screening via Sumsub, Persona or Jumio. | Verified Digital Identity Record. |
| 2. Eligibility Accreditation | Income/net worth documentation review, tax residency determination, country-code logging. | On-chain Identity Claim Attestation minted by trusted issuer. |
| 3. Wallet Authorization | Investor registers an institutional custody address or self-custody Web3 wallet. | Wallet address linked to verified Identity Registry. |
| 4. Subscription & Settlement | Investor signs digital Subscription Agreement; transmits fiat (USD/EUR) or stablecoins (USDC) to escrow. | Subscription clearance notification. |
| 5. Primary Minting | Smart contract mints tokens directly to the verified investor wallet. | On-chain balance credited; cap table updated in real time. |
Step 7: Asset Servicing, Reporting and Corporate Actions
Once tokens are distributed, the platform automates ongoing administrative, reporting and financial servicing tasks throughout the asset’s lifecycle.
- Automated Yield & Dividend Distribution: Asset revenue (e.g., rental income or bond coupons) routes to a distribution smart contract. Investors claim payouts in stablecoins (USDC) or automated bank transfers using real-time cap table snapshots.
- On-Chain Corporate Governance: Enables token holders to vote on asset improvements or sale proposals through cryptographic transactions weighted by token holdings.
- Real-Time Cap Table & Tax Reporting: Maintains a dynamic cap table and generates IRS Form 1099/K-1 exports and regulatory disclosures.
Step 8: Secondary Market Trading and Token Redemption
Tokenization provides liquid secondary trading avenues for traditionally illiquid real-world assets.
- Compliant Secondary Trading: Tokens are listed on regulated secondary venues, such as US Alternative Trading Systems (ATS), European Multilateral Trading Facilities or permissioned decentralized liquidity pools. Every peer-to-peer trade executes Step 5 compliance checks, preventing unverified wallets from buying tokens.
- Asset Maturity & Final Redemption: When the underlying asset reaches maturity (e.g., a corporate bond expires or real estate property is sold):
- Net liquidation proceeds are deposited into an audited redemption escrow contract.
- Token holders surrender and burn their digital tokens via the smart contract.
- The contract releases a final pro-rata distribution of cash or stablecoins directly to the verified investor’s bank account or wallet.
How Much Does RWA Tokenization Development Cost?
Real world asset tokenization development costs depend on more than smart contract engineering. Asset due diligence, legal structuring, compliance controls, custody integrations and security audits all contribute to the budget.
The following breakdown examines investment across development stages and platform scopes, helping estimate the resources required to launch a compliant tokenization platform.
A. RWA Tokenization Platform Development Cost
The total real world asset tokenization development cost aligns with the six-stage lifecycle framework, with total RWA tokenization development costs typically ranging from $35,000 to $1M+.
Below is a phase-by-phase cost sheet detailing the specific deliverables, budget ranges and timeline estimates for each stage of the lifecycle.
| Lifecycle Stage | Basic MVP / Single Asset | Enterprise / Multi-Asset | Est. Timeline | Key Cost Drivers & Deliverables |
| 1. Asset Identification & Due Diligence | $2,000 – $10,000 | $25,000 – $100,000+ | 2 – 4 Weeks | Independent asset appraisals, title/lien searches, physical inspections & financial feasibility audits. |
| 2. Legal & Regulatory Structuring | $8,000 – $25,000 | $70,000 – $250,000+ | 4 – 8 Weeks | SPV/LLC formation, Private Placement Memorandums (PPM), securities counsel & regulatory filings. |
| 3. Blockchain & Token Architecture | $2,000 – $5,000 | $20,000 – $50,000 | 1 – 2 Weeks | System architecture design, tokenomics modeling, compliance standard selection (e.g., ERC-3643) & testnet setup. |
| 4. Smart Contracts & Oracle Integration | $6,000 – $20,000 | $50,000 – $150,000+ | 4 – 6 Weeks | Custom contract coding (minting, dividends, allowlist rules) & Chainlink/oracle API integration for Proof of Reserve. |
| 5. Wallet, Custody & UI Integration | $12,000 – $35,000 | $90,000 – $250,000+ | 6 – 10 Weeks | Investor dashboard, admin portal, KYC/AML APIs (e.g., Sumsub), fiat on-ramps & custody setup (e.g., Fireblocks). |
| 6. Testing, Auditing & Launch | $5,000 – $15,000 | $45,000 – $200,000+ | 3 – 5 Weeks | Third-party smart contract security audits, penetration testing, legal reconciliation & mainnet deployment. |
| Total Estimated Launch Cost | $35,000 – $110,000 | $300,000 – $1M+ | 3 – 6 Months | End-to-End Execution |
Note: These estimates are indicative and may vary with asset type, jurisdiction, legal structure, blockchain selection and integration complexity. They exclude ongoing operating expenses, transaction fees and certain third-party service charges unless included in the agreed project scope and vendor contracts.
Key Cost Variables to Watch
Beyond platform scope, several external factors can shift the final budget. The following variables highlight where legal, vendor and security requirements can significantly increase real world asset tokenization development expenses across the project lifecycle.
- Stages 1 & 2 (Off-Chain Overhead): Legal and due diligence fees scale by jurisdiction. Raising capital across multiple countries requires separate legal opinions and securities exemptions, which can double Stage 2 expenses.
- Stage 5 (Third-Party SaaS Licenses): Beyond developer hours, KYC/AML providers and institutional custodians often require upfront annual setup fees ranging from $5,000 to $25,000 before launch.
- Stage 6 (Audit Tier): An automated or boutique smart contract audit costs around $7,000–$15,000, whereas Tier-1 institutional auditors (such as OpenZeppelin or Trail of Bits) start around $40,000+ per engagement.
B. Cost Tiers by Platform Scope
Developing a Real-World Asset (RWA) tokenization platform typically costs between $35,000 and $1M+ for the initial technical build.
Unlike traditional dApps, RWA platforms bridge blockchain tokens with complex off-chain legal and regulatory systems. Consequently, total investment depends heavily on asset class, compliance requirements and platform complexity. The overall real world asset tokenization development cost scales depending on the type of application you intend to launch:
| Platform Type | Estimated Cost Range | Target Audience & Features |
| Minimum Viable Product (MVP) | $35,000 – $110,000 | Single asset type, basic investor dashboard, basic smart contracts (e.g., ERC-3643), manual compliance workflows. |
| Mid-Level Platform | $120,000 – $200,000 | Automated KYC/AML, investor verification, integration with professional custodians, basic asset management tools. |
| Enterprise / Institutional Platform | $300,000 – $1M+ | Supports multiple assets and chains, institutional custody, multi-jurisdictional compliance, automated dividends and a secondary marketplace. |
Note: These tiers represent indicative build budgets rather than fixed quotes. Final pricing depends on asset classes, investor volume, supported jurisdictions, blockchain networks, automation depth and security standards. Licensing, legal advisory, custody, audits and post-launch maintenance may add costs beyond the build.
C. Breakdown by Core Component
When building a custom RWA platform, the engineering budget is generally divided across these primary layers:
- Smart Contract Engine ($10,000 – $40,000): Writing, testing and hardening permissioned token structures that enforce investor eligibility rules natively on-chain.
- Frontend & Backend Development ($25,000 – $80,000): Building the investor onboarding portals, admin panels, asset listing layouts and portfolio tracking systems.
- Compliance & Identity Layer ($5,000 – $30,000): Integrating programmatic API calls to third-party identity verification vendors for automated KYC, KYB and AML screenings.
- Custody & Payment Systems ($15,000 – $50,000): Integrating institutional-grade digital asset custody (like Fireblocks or BitGo) and linking bank-grade fiat/stablecoin payment gateways.
D. Hidden & Ongoing Operational Costs
Many founders under-budget for RWA launches because they only account for the initial software build. Because RWAs are strictly tied to real-world regulations, you must plan for significant recurring overhead:
- Smart Contract Audits ($5,000 – $25,000+): Security audits by reputable firms are non-negotiable prior to launch and are often repeated after major upgrades.
- Legal & Structural Counsel ($10,000 – $100,000+): Creating the legal wrappers (SPVs), drafting investment prospectuses and ensuring compliance with financial authorities (like the SEC or MiCA).
- Independent Asset Valuation & Audits ($5,000 – $50,000): Ongoing third-party appraisals of the physical or financial assets backing your tokens.
- Ongoing Operations: Expect $3,000 to $25,000+ per month in recurring costs for oracle feeds (Proof of Reserves), per-user KYC checks, ongoing regulatory reporting and legal maintenance.
SPV vs Direct Tokenization: Which Structure Should You Choose?
The legal structure determines the relationship between a digital token and the underlying real-world asset. Businesses generally consider two approaches: issuing tokens that represent interests in an asset-holding entity, such as a Special Purpose Vehicle (SPV) or issuing a tokenized security directly through the asset issuer.
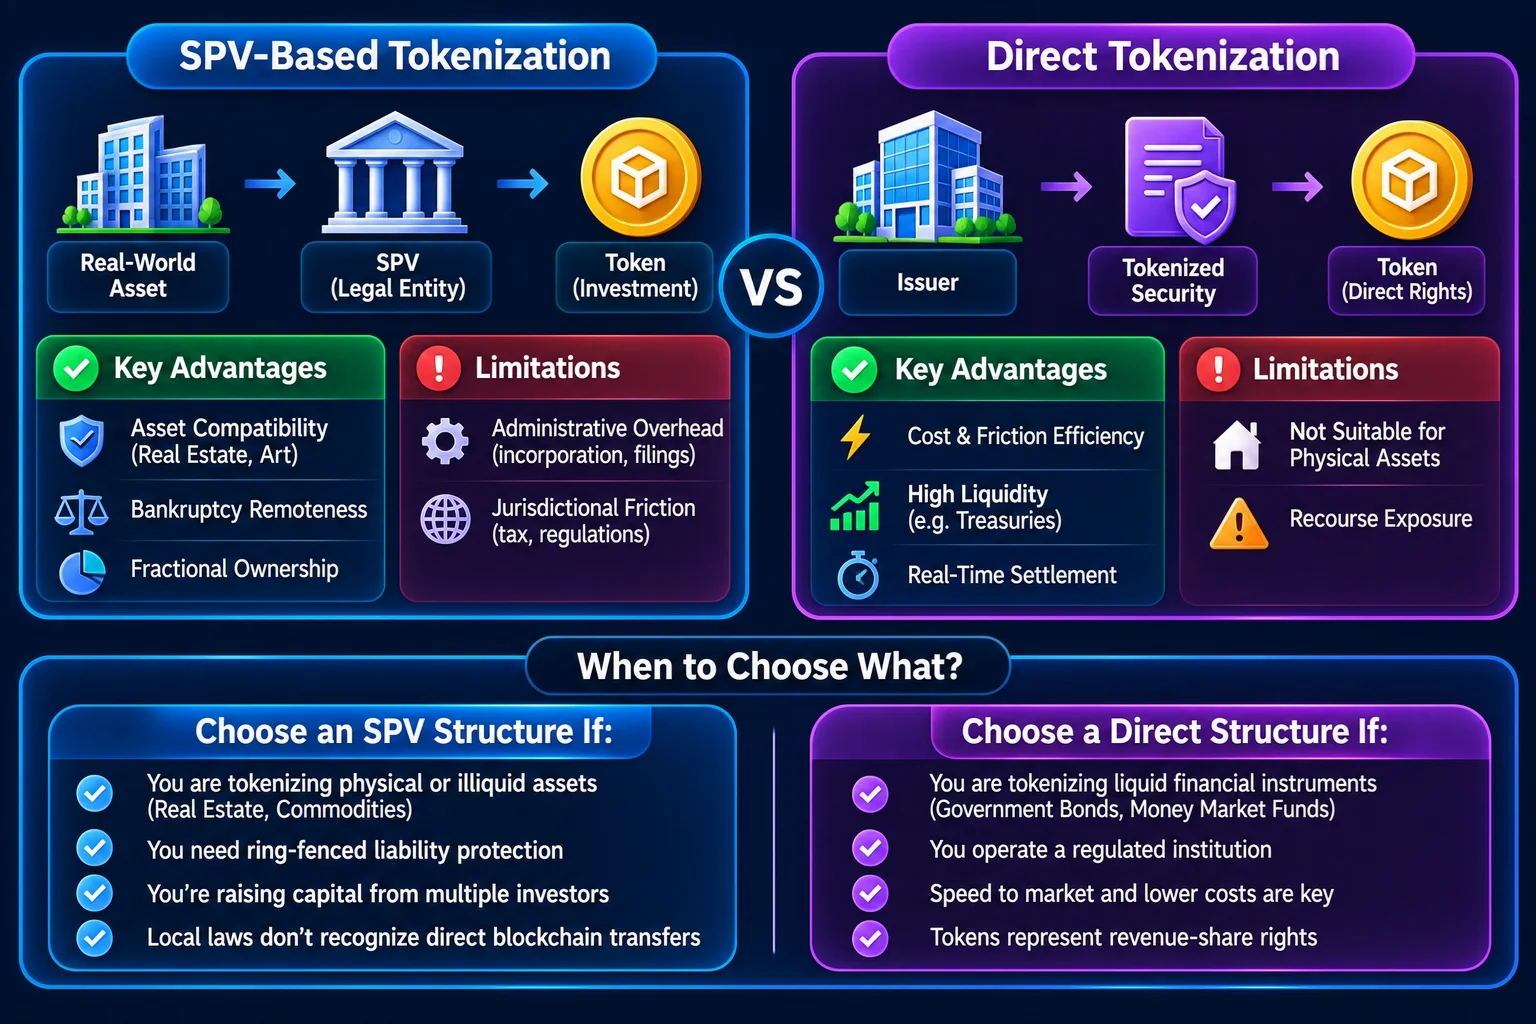
These structures are not interchangeable. The appropriate model depends on the asset, jurisdiction, ownership rights and applicable securities regulations.
The core distinction lies in what the token cryptographically and legally represents: a fractional claim on a dedicated legal entity holding the physical asset (SPV) or a direct legal right to an underlying asset or contract without an intermediary company (Direct).
A. SPV-Based Tokenization
An SPV is a separate legal entity established to hold a particular asset or investment. In a real estate tokenization project, for example, an SPV may acquire and legally own a property. The SPV then issues shares, membership interests or other investment instruments that can be represented by digital tokens.
Investors hold tokens representing rights in the SPV or its issued securities rather than automatically becoming direct legal owners of the underlying property.
Key Advantages
This structure in real world asset tokenization development offers several operational and legal benefits, particularly when managing complex ownership arrangements and protecting investments from unrelated business liabilities.
- Universal Asset Compatibility: Essential for tangible physical property (commercial real estate, equipment, fine art) where municipal land registries or physical titles do not recognize blockchain entries as valid legal ownership transfers.
- Bankruptcy Remoteness & Liability Isolation: If the platform sponsor or asset manager defaults, the SPV assets remain legally protected from main company creditors. Conversely, lawsuits tied to a specific property (e.g., premises liability) are capped to that single SPV.
- Turnkey Fractionalization: Translates complex corporate rights (cash flow distribution, voting rights, liquidation proceeds) into standardized permissioned security tokens (e.g., ERC-3643).
Limitations
Despite these benefits, maintaining separate legal entities introduces recurring obligations and structural challenges that can affect long-term operational efficiency.
- Administrative Overhead: Every individual asset requires legal incorporation, annual tax filings (e.g., K-1s or 1099s), corporate secretarial maintenance and registered agent fees.
- Jurisdictional Friction: Cross-border taxation (withholding taxes, double taxation treaties) can complicate yield distributions to global retail investors.
B. Direct Tokenization
Direct tokenization generally refers to an issuer recording a security or ownership interest directly on a blockchain rather than issuing an interest through a separate asset-holding SPV.
For example, a company may issue tokenized shares with the blockchain serving as part of its authoritative shareholder record. The rights attached to the tokens must still be established under the applicable legal and corporate framework.
The SEC’s January 2026 statement describes issuer-sponsored tokenized securities where the issuer or its agent integrates distributed ledger technology into the system used to record security ownership. It also makes clear that using blockchain does not remove the application of securities laws.
Key Advantages
This approach can simplify operational structures and reduce intermediary dependencies, making it suitable for standardized financial products that support streamlined digital transactions.
- Maximum Cost & Friction Efficiency: Eliminates SPV incorporation fees, redundant legal structures and multi-tiered corporate administration.
- High Liquidity & Scalability: Ideal for highly standardized financial instruments like US Treasury bills (e.g., Ondo OUSG, BlackRock BUIDL), short-term commercial paper or digital invoice factoring.
- Real-Time Settlement: Direct integration between on-chain smart contracts and institutional custodians enables rapid primary minting and redemption cycles.
Limitations
However, removing the separate holding entity can introduce legal and financial constraints, particularly when dealing with tangible assets or issuer-level obligations.
- Unsuitable for Physical Assets: Physical assets like real estate cannot be tokenized directly without a legal wrapper because local laws require registered legal entities or natural persons on property titles.
- Recourse Exposure: Without an SPV, claims or liabilities associated with the asset could flow directly to the parent issuer’s balance sheet.
C. SPV vs Direct Tokenization: Key Differences
SPV and direct tokenization differ in ownership structure, asset suitability, liability exposure and legal requirements. The following comparison highlights their key structural and operational differences.
| Structural Dimension | SPV Tokenization Model | Direct Tokenization Model |
| Legal Definition | Separate asset-holding entity | Issuer directly issues the security |
| Asset Types Supported | Physical and illiquid assets: Real estate, private equity, fine art, infrastructure, commodities and debt portfolios. | Digital and standardized assets: Treasury bills, public securities, carbon credits, invoice & revenue sharing. |
| Liability Exposure | Ring-fenced (Protected): Asset-related liabilities remain isolated within the bankruptcy-remote SPV. | Direct Risk: The issuer or primary entity remains exposed to asset-level liabilities. |
| Regulatory Classification | Generally classified as a Security (Securities Act, MiFID II, Reg D/S/A+). | Classified as Securities, Derivatives or Commodities, depending on instrument design. |
| Setup Cost & Complexity | Higher legal setup costs ($15,000–$60,000+/SPV) + annual maintenance. | Lower entity maintenance fees but higher initial smart contract and legal wrapper engineering costs. |
| Off-Chain Title Sync | Seamless: Land registries or title deeds record the SPV as owner, while tokens track its cap table. | Complex: Requires local property registries to recognize blockchain records as legal title transfers. |
D. Which structure should you choose?
An SPV structure isolates specific assets within separate entities, whereas direct tokenization lets existing issuers represent securities on-chain.
Neither method guarantees investor protection, legal ownership or liquidity, as enforceable rights depend on legal instruments, ownership records and jurisdiction.
A 2026 academic paper in the European Journal of Risk Regulation also explains how SPVs and funds can act as intermediary legal structures in tokenization, with tokens representing interests in those entities rather than direct title to the physical asset.
Choose an SPV Structure if:
This model is particularly relevant when asset-level separation, established corporate arrangements and investor participation requirements shape the overall investment structure.
- You are tokenizing physical or illiquid assets (Real Estate, Commodities, Collectibles, Equipment, Aviation).
- You require ring-fenced liability protection to insulate individual assets from tenant lawsuits, debt defaults or platform-level risks.
- You are raising capital from multiple un-accredited or syndicated investors, requiring a standardized equity or debt issuer vehicle.
- Local legal title registries do not recognize direct blockchain transactions as legal conveyances of property title.
Choose a Direct Structure if:
This approach is better suited to financial products and digital instruments where existing institutional frameworks can support streamlined issuance and administration.
- You are tokenizing liquid, standardized financial instruments (Government debt, AAA corporate bonds, money market funds, trade receivables).
- You operate a licensed financial institution or regulated trust capable of directly holding underlying securities with a qualified custodian.
- Speed to market and operational cost reduction are your primary business metrics and your underlying assets carry no physical liability risks.
- Your tokens represent programmatic revenue-share rights directly bound to an operating software protocol or digital contract.
Which Token Standards Are Used in RWA Tokenization?
Tokenizing real-world assets (RWAs) such as real estate, private equity, debt and commodities demands strict regulatory compliance. Basic permissionless standards (like ERC-20 or ERC-721) are inadequate because they lack native identity verification, transfer restrictions and legal clawback capabilities.
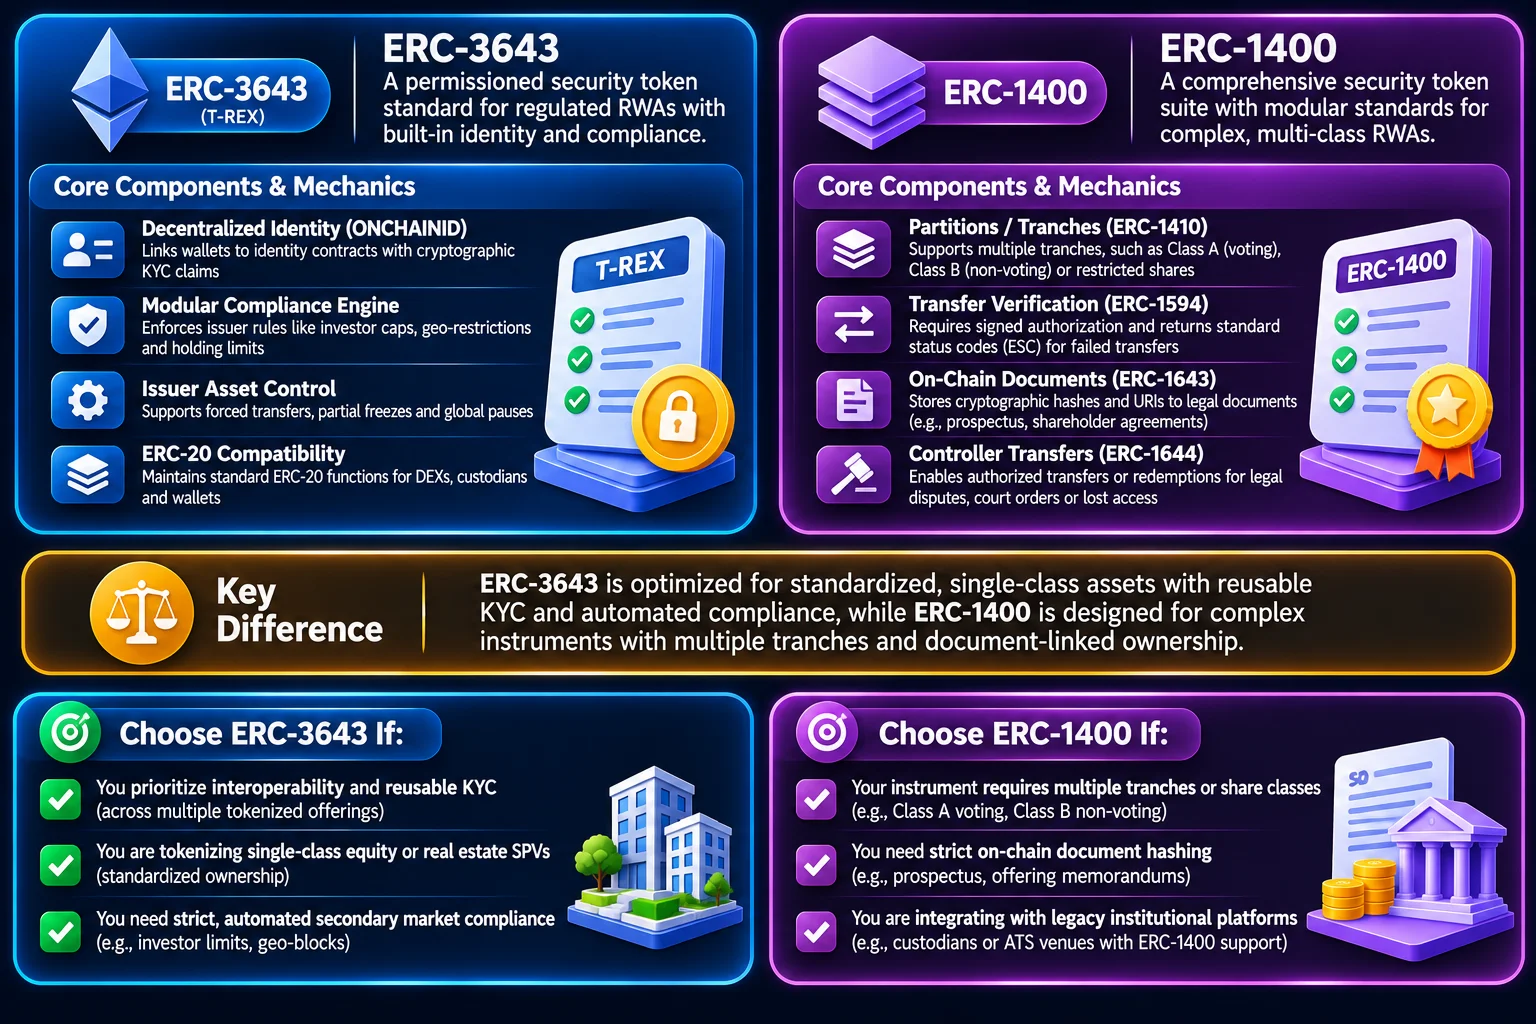
To bridge traditional finance (TradFi) compliance with public or private EVM-compatible blockchains, two primary permissioned token frameworks have emerged: ERC-3643 and ERC-1400.
A. ERC-3643: Permissioned Security Tokens
ERC-3643, also known as T-REX, officially finalized Ethereum Improvement Proposal (EIP) is designed for regulated security tokens that require investor identity verification and compliant transfers.
It builds on ERC-20 compatibility while adding identity registries and compliance mechanisms that validate whether a recipient can legally hold a token.
Core Components & Mechanics
- Decentralized Identity Integration (ONCHAINID): ERC-3643 connects investor wallets to ONCHAINID identity contracts rather than storing personal data on-chain. Approved issuers then sign cryptographic claims (such as KYC or accredited status) within this identity layer.
- Modular Compliance Engine: An external Compliance contract checks every transfer against issuer-defined rules including investor caps (e.g., 2,000 holders), geographical restrictions and maximum holding percentages.
- Issuer Asset Control: The token contract provides issuers and authorized agents with administrative controls including forced transfers for court orders or lost keys, partial freezes and global pauses.
- ERC-20 Backward Compatibility: The interface maintains standard ERC-20 functions (transfer, balanceOf) for compatibility with DEXs, custodial vaults and Web3 wallets while enforcing background transfer controls.
For example, a tokenized real estate investment offered only to eligible investors can use ERC-3643-compatible mechanisms to restrict transfers to verified wallets.
B. ERC-1400: Security Token Standard Suite
ERC-1400 (Introduced in 2018, spearheaded by Polymath) is a comprehensive, multi-part security token standard suite. It operates as an umbrella framework combining related sub-standards including ERC-1410, ERC-1594, ERC-1643 and ERC-1644.
Core Components & Mechanics
- Differentiated Partitions / Tranches (ERC-1410): Supports token partitions within one contract, allowing wallets to hold different tranches such as Class A Voting Shares, Class B Non-Voting Shares or Locked Restricted Shares.
- Explicit Transfer Verification (ERC-1594): Requires signed off-chain authorization or operator signatures before transfers. It returns bytecode status codes (ESC reason codes) explaining transaction failures.
- On-Chain Document Management (ERC-1643): Stores cryptographic hashes and URI links to legal documents (prospectuses, offering memorandums and shareholder agreements) in the token contract, linking ownership to legal terms.
- Forced Controller Transfers (ERC-1644): Allows designated legal operators to execute controller transfers or token redemptions for legal disputes, court orders or lost-access recovery.
For example, a security token with different investor classes or transfer restrictions may use partitioning to distinguish how different portions of a holder’s balance behave.
C. ERC-3643 vs ERC-1400
ERC-3643 and ERC-1400 support regulated security token issuance but differ in identity management, compliance enforcement and token functionality. The following comparison highlights their technical capabilities, suitable applications and ecosystem adoption.
| Architectural Metric | ERC-3643 (T-REX Framework) | ERC-1400 (Security Token Suite) |
| Standard Status | Official Finalized EIP Standard (Final status). | Collection of EIP drafts (widely implemented, but structured as a family of sub-standards). |
| Identity Management | On-Chain Identity Registry (ONCHAINID): Separates identity from the token contract and reuses KYC attestations across issuers and assets. | Off-Chain / Address Allowlist: Uses signed off-chain attestations or address allowlists for transfers. |
| Compliance Checking | Modular & Automated: Checks identity registries and external compliance engines on every transfer. | Operator / Signature-Based: Uses off-chain signed payloads or custom transfer verification logic. |
| Special capabilities | Freezing, pausing, recovery and agent roles | Partitioning, document management, issuance, redemption and controller operations |
| Suitable applications | Regulated RWA offerings requiring investor eligibility controls | Security tokens requiring differentiated rights, partitions and lifecycle controls |
| Ecosystem & Market Adoption | Institutional adoption, with $30B+ in tokenized value across 120+ financial deployments. | Established implementation base across early security token platforms and institutional builds. |
D. Which standard is better for RWA tokenization?
Neither standard is universally “better”; the optimal selection depends entirely on your underlying asset structure and market integration strategy.
Choose ERC-3643 if:
This standard fits platforms that emphasize repeatable investor onboarding, consistent ownership structures and automated eligibility enforcement across regulated token transfers.
- You prioritize interoperability and reusable KYC: Your platform targets global investors who should undergo KYC once and seamlessly trade multiple tokenized offerings across different platforms without repeating onboarding.
- You are tokenizing single-class equity or real estate SPVs: For standard real estate, private equity or fund tokenization where each token represents a uniform share, ERC-3643 provides an elegant, gas-efficient architecture.
- You require strict, automated secondary market compliance: You want on-chain compliance rules (e.g., investor limits, geographical blocks) enforced automatically on peer-to-peer transfers without requiring custom off-chain signing keys.
Choose ERC-1400 if:
This standard suits complex financial instruments that require differentiated investor rights, document-linked ownership records and compatibility with established institutional systems.
- Your financial instrument requires multiple tranches or share classes: If a single asset has Class A Voting, Class B Non-Voting or multi-tiered debt coupons that must live under one token smart contract, ERC-1400’s native partition engine excels.
- You need strict on-chain document hashing: Your legal structuring requires binding the token directly to on-chain legal prospectus hashes via ERC-1643.
- You are integrating with legacy institutional platforms: You are connecting to existing institutional custodians or ATS venues whose backend systems are pre-built to ingest ERC-1400 interface calls.
What Are The Challenges To Build RWA Tokenization Platform?
The real world asset tokenization development involves more than issuing blockchain tokens. Developers must connect legal eligibility rules, verified asset records and financial operations with secure on-chain workflows. Three engineering challenges require particular attention during platform architecture, integration and deployment decisions.
1. Cross-Jurisdictional Compliance Logic
Challenge: Encoding investor eligibility, transfer restrictions and jurisdiction-specific securities rules consistently across smart contracts and off-chain onboarding systems creates enforcement complexity.
Solution: Our developers map legal requirements into configurable compliance services, integrate identity verification and allowlist checks, then enforce transfer rules in contracts and backend APIs with auditable, transaction-level decision logs.
2. Asset Data Synchronization and Reconciliation
Challenge: Asset ownership, valuations, income events and token balances can diverge across custodians, registries and blockchain networks, creating costly errors.
Solution: We build integration layers with validated APIs, event-driven updates and a canonical asset ledger, then add reconciliation jobs, exception queues and monitoring to detect mismatches before investor records change downstream.
3. Institutional Custody and Transaction Security
Challenge: Institutional custody, wallet controls, payment rails and token contracts must interoperate securely without weakening transaction authorization or settlement reliability standards.
Solution: Our developers define role-based signing policies, integrate vetted custody and payment providers, apply HSM-backed key controls and validate recovery and settlement paths with regular end-to-end tests before each production release.
How Idea Usher Can Build Your RWA Tokenization Platform?
Tokenizing real-world assets (RWAs) like real estate, private credit, funds, commodities, and treasuries requires connecting legal wrappers with on-chain liquidity.
The challenge is not merely minting tokens; it is engineering a platform that synchronizes dynamic cap tables with legal registers, automates yield payouts, enforces jurisdictional transfer rules, and provides auditable institutional custody.
IdeaUsher is an enterprise product engineering partner with 11+ years of experience, 250+ technologists, a 4.9/5 Clutch rating and 1,000+ delivered builds. We construct custom RWA tokenization platforms focused on compliance, liquidity, and code sovereignty.
A. Custom Smart Contracts & Programmable Compliance
Our developers engineer permissioned token frameworks that automate investor eligibility, transfer restrictions and legal record synchronization while maintaining compliance across asset ownership structures.
- Permissioned Token Frameworks: ERC-3643, ERC-1400 and customized ERC-20/ERC-1155 contracts enforce accreditation, lockups and transfer restrictions.
- On-Chain Identity & Allowlisting: ERC-734/ERC-735 identity protocols connect KYC/AML, sanctions screening and jurisdictional eligibility to investor wallets.
- Cap Table & Legal Synchronization: Reconciliation pipelines synchronize token transfers with SPV registers, trust agreements and transfer agent records.
B. End-to-End Asset Lifecycle, Yield & Cashier Infrastructure
We build integrated financial infrastructure that connects investor onboarding, institutional custody and automated distributions with verifiable asset reserves and payment workflows.
- Automated Yield & Dividend Distribution: Payment-splitter contracts and cash flow waterfalls automate rental yields, loan coupons and revenue distributions in USDC or USDT.
- Multi-Rail Onboarding & Account Abstraction: ERC-4337, paymasters, social logins, fiat gateways and Web3 wallets simplify investor onboarding.
- Institutional Custody & Reserve Oracles: MPC custody through Fireblocks or Safe, combined with Chainlink Proof of Reserve, verifies treasury security and asset backing.
C. Scalable Platform Architecture & Secondary Market Liquidity
Our engineering teams develop scalable indexing, trading and cloud infrastructure to support investor reporting, compliant secondary transactions and long-term platform ownership.
- High-Throughput Subgraph Indexing: The Graph and caching microservices deliver real-time cap tables, portfolio data and transaction histories.
- Compliant Secondary Trading: Permissioned AMMs, P2P liquidity boards and ATS or broker-dealer API integrations enable verified investor trading.
- Cloud Architecture & IP Ownership: Kubernetes-based microservices support scalability, while documented source code ensures full IP ownership and zero vendor lock-in.
Planning to tokenize private credit, real estate, or commodity portfolios?
Connect with Idea Usher’s blockchain software architects to evaluate your legal-to-technical mapping, smart contract requirements, and technical real world asset tokenization development roadmap.
Conclusion
The future of asset ownership is increasingly connected to blockchain infrastructure, but successful tokenization depends on more than issuing digital tokens. Legal structuring, asset custody, investor compliance, smart contract security and secondary market access must work together. A well-planned real world asset tokenization development strategy helps businesses establish this foundation while accounting for regulatory obligations and operational complexity. IdeaUsher brings blockchain engineering expertise to these requirements, helping businesses turn their RWA concepts into secure, scalable and market-ready platforms.
FAQs
A.1. Real world asset tokenization development costs range from $50,000–$150,000 for an MVP, $100,000–$250,000 for a production platform and $250,000–$1 million+ for enterprise solutions, depending on compliance, custody and asset complexity.
A.2. A white-label deployment takes 4–8 weeks, a custom MVP real world asset tokenization development requires 3–5 months and a production platform takes 6–9 months. Enterprise projects may require 9–18 months, depending on integrations and regulatory approvals.
A.3. A Special Purpose Vehicle (SPV) is a separate legal entity established to hold an asset and issue investment interests represented by digital tokens. Investors typically hold SPV interests rather than direct asset ownership.
A.4. Yes, but token ownership does not automatically establish legal title to a physical asset. Recognized ownership transfers depend on the asset type, jurisdiction and governing legal documents.
A.5. Yes, when tokens represent shares, debt instruments, fund interests or securities under applicable laws. Regulatory obligations depend on token rights, offering structures, investor classifications and jurisdictions.
A.6. Ethereum supports standards such as ERC-3643 and ERC-1400, while alternative networks offer different costs and performance. Selection depends on asset type, compliance, transaction volume, custody and interoperability requirements.